Energy Tax Relief

British Industrial Competitiveness Scheme

Prepare your business to benefit from lower electricity costs under BICS from 2027.

Our Energy Tax Relief Specialists will assess your eligibility and help you prepare your BICS application before the first application window opens in October 2026.
British Industrial Competitiveness Scheme

What is BICS?

The British Industrial Competitiveness Scheme is a government electricity cost relief scheme for eligible manufacturers in Great Britain.

It will exempt those manufacturers from part or all of the indirect costs of the Renewables Obligation, Feed-in Tariffs and Capacity Market. The exemption will reduce the policy-related costs that electricity suppliers include in business electricity prices.

The Renewables Obligation and Feed-in Tariffs exemptions are scheduled to begin in April 2027, followed by the Capacity Market exemption in October 2027.

The first application will also include a back-dated payment for the 2026 year, which will further support eligible businesses.

uk-small-map
1 (3)
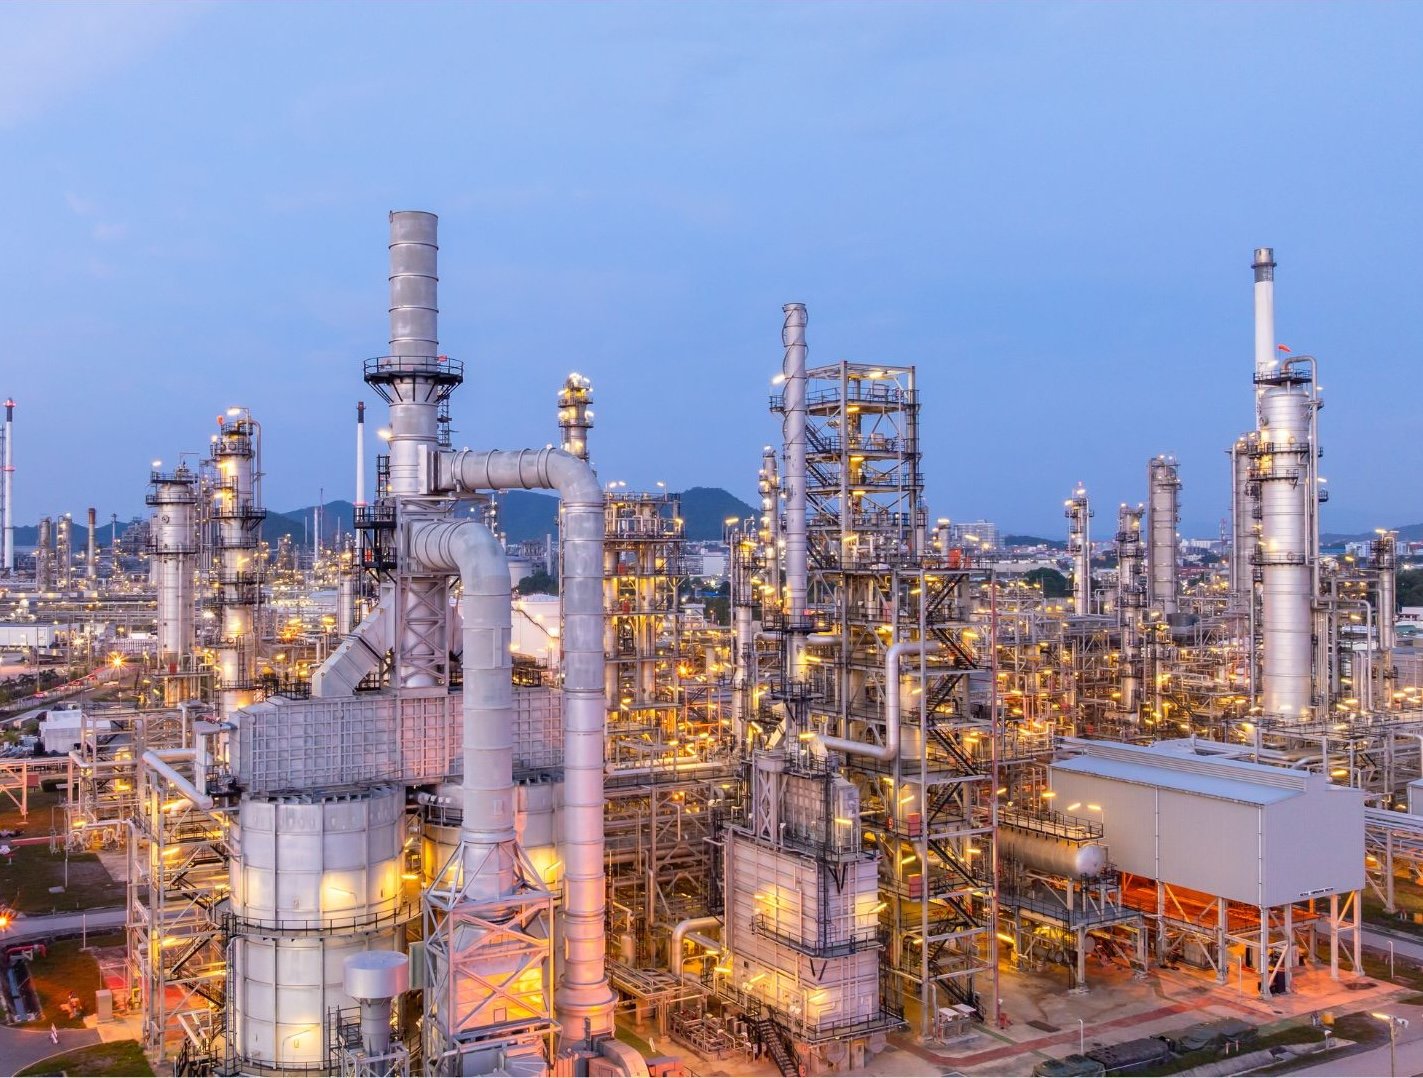
Industrial Plant
technical-expert-icon

How is electricity intensity assessed for BICS?

The government assessed electricity intensity at sector level when selecting the manufacturing activities covered by BICS. We complete any required electricity-intensity calculation on the applicant’s behalf as part of the application process.

Manufacturing Activities and Products Eligible for BICS

The final BICS lists cover selected manufacturing activities and products across advanced manufacturing, clean energy, defence, digital technologies and life sciences. They also cover foundational manufacturing industries that supply products and materials to those sectors.


BICS Eligible Manufacturing

At a broad level, eligible manufacturing activities include specific areas of:

  • Chemicals and advanced materials
  • Pharmaceuticals and medical manufacturing
  • Glass, ceramics and construction materials
  • Iron, steel and non-ferrous metals
  • Electrical and electronic equipment
  • Batteries, machinery and industrial equipment
  • Automotive, aerospace, shipbuilding and defence manufacturing
  • Recycling and materials recovery


These categories provide an overview only. The business must carry out an activity covered by a code on the final BICS SIC list.


Manufacturing Frontier Industries

  • 2011 — Manufacture of industrial gases
  • 2051 — Manufacture of explosives
  • 2110 — Manufacture of basic pharmaceutical products
  • 2120 — Manufacture of pharmaceutical preparations
  • 2211 — Manufacture of rubber tyres and tubes; retreading and rebuilding of rubber tyres
  • 2319 — Manufacture and processing of other glass, including technical glassware
  • 2344 — Manufacture of other technical ceramic products
  • 2433 — Cold forming or folding
  • 2446 — Processing of nuclear fuel
  • 2521 — Manufacture of central heating radiators and boilers
  • 2530 — Manufacture of steam generators, except central heating hot water boilers
  • 2562 — Machining
  • 2599 — Manufacture of other fabricated metal products n.e.c.
  • 2611 — Manufacture of electronic components
  • 2612 — Manufacture of loaded electronic boards
  • 2660 — Manufacture of irradiation, electromedical and electrotherapeutic equipment
  • 2670 — Manufacture of optical instruments and photographic equipment
  • 2711 — Manufacture of electric motors, generators and transformers
  • 2712 — Manufacture of electricity distribution and control apparatus
  • 2720 — Manufacture of batteries and accumulators
  • 2731 — Manufacture of fibre optic cables
  • 2732 — Manufacture of other electronic and electric wires and cables
  • 2733 — Manufacture of wiring devices
  • 2790 — Manufacture of other electrical equipment
  • 2811 — Manufacture of engines and turbines, except aircraft, vehicle and cycle engines
  • 2812 — Manufacture of fluid power equipment
  • 2813 — Manufacture of other pumps and compressors
  • 2814 — Manufacture of other taps and valves
  • 2815 — Manufacture of bearings, gears, gearing and driving elements
  • 2825 — Manufacture of non-domestic cooling and ventilation equipment
  • 2830 — Manufacture of agricultural and forestry machinery
  • 2849 — Manufacture of other machine tools
  • 2899 — Manufacture of other special-purpose machinery n.e.c.
  • 2910 — Manufacture of motor vehicles
  • 2920 — Manufacture of bodies (coachwork) for motor vehicles; manufacture of trailers and semi-trailers
  • 2932 — Manufacture of other parts and accessories for motor vehicles
  • 3011 — Building of ships and floating structures
  • 3030 — Manufacture of air and spacecraft and related machinery
  • 3040 — Manufacture of military fighting vehicles
  • 3250 — Manufacture of medical and dental instruments and supplies
  • 3299 — Other manufacturing n.e.c.
  • 3316 — Repair and maintenance of aircraft and spacecraft
  • 3521 — Manufacture of gas
  • 3821 — Treatment and disposal of non-hazardous waste

Manufacturing Foundational Industries

  • 1041 — Manufacture of oils and fats
  • 1062 — Manufacture of starches and starch products
  • 1081 — Manufacture of sugar
  • 2013 — Manufacture of other inorganic basic chemicals
  • 2014 — Manufacture of other organic basic chemicals
  • 2015 — Manufacture of fertilisers and nitrogen compounds
  • 2016 — Manufacture of plastics in primary forms
  • 2017 — Manufacture of synthetic rubber in primary forms
  • 2060 — Manufacture of man-made fibres
  • 2221 — Manufacture of plastic plates, sheets, tubes and profiles
  • 2229 — Manufacture of other plastic products
  • 2311 — Manufacture of flat glass
  • 2312 — Shaping and processing of flat glass
  • 2313 — Manufacture of hollow glass
  • 2314 — Manufacture of glass fibres
  • 2343 — Manufacture of ceramic insulators and insulating fittings
  • 2351 — Manufacture of cement
  • 2352 — Manufacture of lime and plaster
  • 2363 — Manufacture of ready-mixed concrete
  • 2364 — Manufacture of mortars
  • 2399 — Manufacture of other non-metallic mineral products n.e.c.
  • 2410 — Manufacture of basic iron and steel and of ferro-alloys
  • 2420 — Manufacture of tubes, pipes, hollow profiles and related fittings, of steel
  • 2431 — Cold drawing of bars
  • 2432 — Cold rolling of narrow strip
  • 2434 — Cold drawing of wire
  • 2441 — Precious metals production
  • 2442 — Aluminium production
  • 2443 — Lead, zinc and tin production
  • 2444 — Copper production
  • 2445 — Other non-ferrous metal production
  • 2451 — Casting of iron
  • 2452 — Casting of steel
  • 2453 — Casting of light metals
  • 2454 — Casting of other non-ferrous metals
  • 2529 — Manufacture of other tanks, reservoirs and containers of metal
  • 2550 — Forging, pressing, stamping and roll-forming of metal; powder metallurgy
  • 2561 — Treatment and coating of metals
  • 2593 — Manufacture of wire products, chain and springs
  • 3832 — Recovery of sorted materials
join-us-video-bnr-1
Our Services

How we help Manufacturing businesses

A BICS application requires more than confirming that your business meets the main eligibility conditions. It must show that your manufacturing activities and products qualify for the scheme. It must also support the exemption level calculated from the eligible electricity use at each site. Incomplete records or incorrect allocation of electricity use can affect the outcome.

Our compliance guarantee: Our energy specialists ensure a clear basis for the application and check that each conclusion is supported by the available business records before submission.
Energy People
Oct 2026

BICS Application Management

  • Eligibility

Reduce your electricity costs under BICS from 2027. Eligible manufacturers could save up to 25% on their total electricity bill.
  • SIC Code VerificationWe confirm your manufacturing activities against the final BICS eligible SIC code list
  • HS Code AssessmentWe check your products against the final BICS eligible HS code list on your behalf
  • Electricity Use AllocationWe calculate the proportion of electricity attributable to eligible manufacturing at each site
  • Savings EstimateWe provide an initial estimate of the potential reduction in electricity costs across your sites
Energy Allocation
£35–40/MWh

Savings with BICS

  • Application
We manage the full BICS application process, from initial assessment through to submission within the first window.
  • BICS Eligibility AssessmentWe confirm whether your manufacturing activities and products meet the scheme criteria
  • Exemption Level CalculationWe determine the correct exemption level for each of your manufacturing sites
  • Application PreparationWe compile the required records and prepare your submission before the window opens
  • Submission SupportWe prepare and support submission ahead of the 1 October 2026 application window
Energy Savings
Up to 25%

Potential Electricity Cost Reduction

  • Savings

We estimate the potential BICS saving across your manufacturing sites before you decide to proceed with a full application. The proportion of exemption is calculated by dividing the electricity used for eligible manufacturing by the site’s total electricity use.
  • Site-by-Site AnalysisEach manufacturing site is assessed separately to determine the applicable exemption level
  • 50% Exemption BandSites where 25–49% of electricity use relates to eligible manufacturing qualify for a 50% exemption
  • 100% Exemption BandSites where 50% or more of electricity use relates to eligible manufacturing qualify for a full exemption
Solar Installation
All Sites

Groups, Shared Supplies and Private Networks

  • Complex Structures

We identify the correct applicant and confirm which electricity use and costs should be included where group or shared supply arrangements apply.

  • Group StructuresWe establish the correct applicant where another group company holds the energy contract
  • Shared SuppliesWe identify the eligible electricity use where several businesses share one supply
  • Private NetworksWe verify passed-through policy costs where electricity is provided through a landlord or private network
  • Specialist GuidanceOur Energy Tax Relief Specialist confirms which costs should be included in the application
download-icon

Additional Payment for Eligible First-Year Businesses

Businesses confirmed as eligible in the first year will receive a separate one-off payment after BICS launches. The payment will reflect the support they would have received if BICS had been operating from April 2026. The government has not yet confirmed the payment date.

Speak with our Energy Tax Relief Specialist now to check your likely eligibility and prepare your business before the first BICS application window opens.

The published timetable is subject to parliamentary approval of the secondary legislation required to implement BICS.

Meet Our Team

Dedicated Energy Experts

Bonham & Brook assigns each business relief scheme to specialists with relevant sector expertise.

Your BICS application will be led by our Energy Tax Relief Specialists, who will remain your direct point of contact from the initial assessment through to submission.
Featured Case Study

Inside Weetabix's energy strategy

Discover how Bonham & Brook supported leading UK food manufacturer Weetabix secure valuable Energy tax relief.

Video Thumbnail

Client Success story 

Weetabix

BICS

Frequently Asked Questions

Your business can still apply after the first window.

From the second year of BICS, the government will provide a longer application window and set a cut-off date for each delivery year. An approved business will enter the scheme at the start of the next relevant delivery year. Mid-year entry will not be available.

BICS eligibility lasts for five years. The Department for Business and Trade will review your eligibility and site exemption levels after the second year. You must also submit an annual declaration confirming whether your circumstances have changed.

At the end of the five-year period, your eligibility and exemption levels will be reassessed.

Yes, you must confirm relevant changes in your annual declaration.

Changes to your electricity supplier, meter number or legal entity may need to be reported during the delivery year. The government will confirm the full reporting requirements in the BICS business guidance.

It may be, but this is not guaranteed.

Your electricity supplier will apply the exemption to the relevant charges and decide how to show the saving on the bill. Government guidance will encourage suppliers to show it separately.

No, a business receiving British Industry Supercharger support cannot also receive BICS.

The schemes cover overlapping electricity policy costs, so the same support cannot be provided twice.

You can start with basic information about your manufacturing activities, products, sites and annual grid electricity use.

Our Energy Tax Relief Specialist will then identify any additional records needed for the review.

Get in Touch

BICS Eligibility Review

Book a structured, no-obligation review with a specialist. We'll assess your manufacturing activities and provide a clear eligibility recommendation.

telephone-call-icon
Confidential

All discussions are held in strict confidence.

user-rounded-icon
Complimentary

Initial eligibility consultation is always complimentary.

user-chat-icon

Request a Free BICS Eligibility Review